
Timing can make the difference between an annuity that works powerfully for your clients and one that simply sits in their portfolio. For businesses and agencies that guide clients through retirement decisions, understanding when an annuity may be appropriate is just as important as understanding how annuities work.
For many households, annuities can provide predictable income, help manage longevity risk, and complement Social Security and pensions. Yet clients often ask, “Should I buy now, or wait?” That question is rarely simple. It involves age, market conditions, tax considerations, and each client’s unique retirement timeline.
This article is designed for businesses and agencies that want a clearer framework to help clients evaluate the timing of annuity purchases: before retirement, at retirement, or later in life. You will also see how market uncertainty, procrastination, and age-related product options can impact the strategy.
Schedule a Tax-Aware Retirement Strategy Call: 👉 https://cindybirkland.com/contact/
1. Clarifying the Core Question: When Is the Right Time?
The “right time” to buy an annuity is less about a magic age and more about a transition point in a client’s financial life. Typically, that transition is when they move from accumulation to distribution, or when risk tolerance and income needs change in a meaningful way. For many, this is within a window that begins roughly 5 to 10 years before retirement and can extend into their early to mid-70s, depending on health and goals.
Your role as an advisor or agency is to help clients identify:
- When they will realistically start drawing income from their assets
- How much guaranteed income they already have from Social Security or pensions
- How uncomfortable they are with market volatility affecting their lifestyle
When those answers point toward a need for more predictable, tax-aware, and structured income, the timing may be appropriate to evaluate annuity solutions. From there, the question becomes whether to purchase before retirement, at retirement, or after retirement has already begun.
2. Before Retirement vs. After Retirement
Buying an Annuity Before Retirement
Many clients in their 50s or early 60s are still working, but they are also beginning to feel the pressure of retirement decisions. For this group, annuities can serve as a pre-retirement positioning tool. They may not need income immediately, but they want to:
- Lock in future income guarantees while they are still relatively young and insurable
- Reduce exposure to large market losses in the final years before retirement
- Create a defined “income bucket” that complements their other investments
Products such as deferred income annuities or fixed indexed annuities with income riders can be particularly attractive in this stage. Clients can let these contracts grow until a planned retirement date, then activate income according to a schedule that aligns with their goals. For agencies, this approach can help build a long-term roadmap instead of a last-minute scramble at retirement.
Buying an Annuity at or After Retirement
Some clients wait until they are on the doorstep of retirement or already retired before considering annuities. This timing can still be effective, especially for those who:
- Have accumulated substantial assets and now want to convert a portion into predictable income
- Have experienced a market scare and want more stability going forward
- Are facing required minimum distributions and want a more tax-aware strategy for those dollars
Immediate income annuities and certain guaranteed lifetime withdrawal benefit (GLWB) riders can be particularly relevant at this stage. The client is not waiting years for income to begin. Instead, they are trading a lump sum for an income stream that can help them meet monthly expenses with less worry about market swings.
Schedule a Tax-Aware Retirement Strategy Call: 👉 https://cindybirkland.com/contact/
3. Using an Annuity During Market Uncertainty
Market uncertainty can be a catalyst for annuity conversations. When clients see headlines about volatility, inflation, or geopolitical risk, they often feel a renewed sense of vulnerability. This is especially true for those within 10 years of retirement, because a major downturn could significantly alter their lifestyle projections.
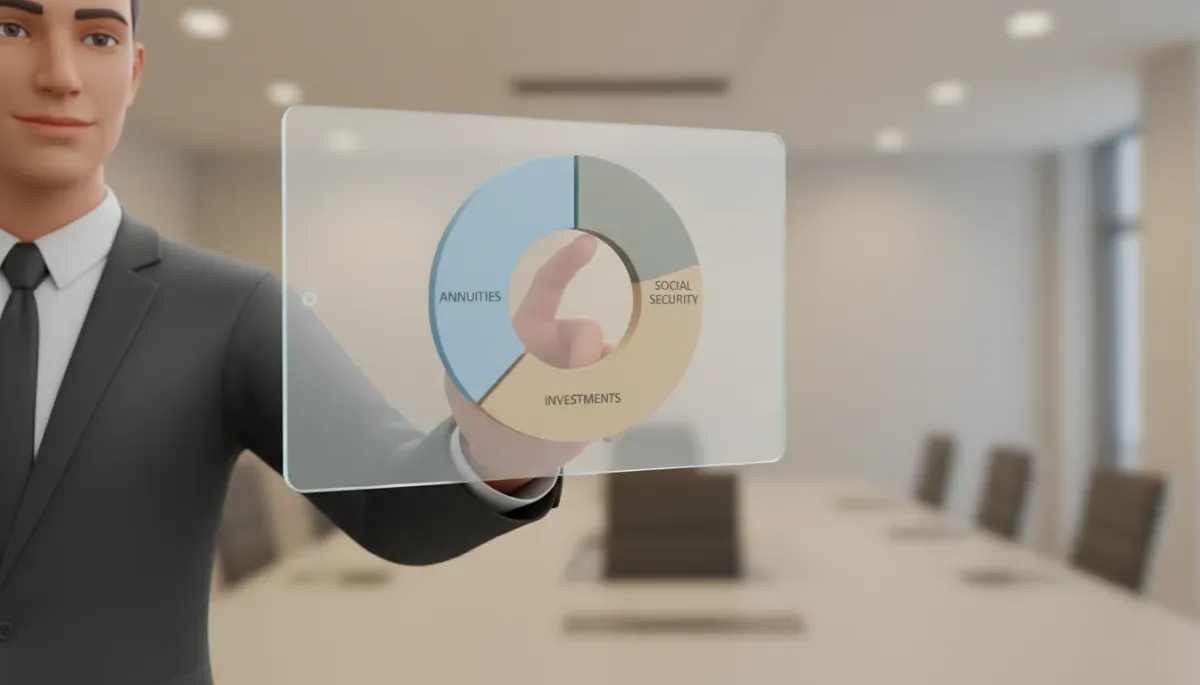
Blending annuities with investments can reduce sequence-of-returns risk in retirement.
In uncertain markets, annuities can serve as a stability anchor within a broader retirement income strategy. Rather than trying to time the market, clients can:
- Shift a portion of assets into vehicles that offer principal protection or guaranteed income, subject to the terms of the contract
- Use annuity income to cover core expenses so they can leave more volatile investments untouched during downturns
- Reduce the emotional pressure to sell at the wrong time because part of their income is already secured
For agencies, this creates an opportunity to reframe annuities not as “products to buy when scared” but as strategic tools that are especially valuable when markets are unpredictable. The timing conversation becomes less about reacting to fear and more about proactively designing a plan that can withstand a wide range of market environments.
4. Common Mistakes When Waiting Too Long
Procrastination is one of the biggest obstacles to effective annuity planning. Clients often delay decisions because they want to “see what the market does,” “wait until rates improve,” or “feel more ready” for retirement. While waiting can sometimes be appropriate, there are several common mistakes that occur when clients delay too long.
Mistake 1: Losing the Power of Deferral
Many annuity strategies work best when given time to grow before income begins. Delaying a purchase until the last possible moment can reduce the potential benefit of deferral credits, roll-up rates, or compounding inside the contract. Clients may end up with lower lifetime income than they could have achieved by starting earlier with a portion of their assets.
Mistake 2: Waiting Until After a Major Market Loss
Another common pattern is that clients ignore annuities during bull markets and only become interested after a significant downturn. At that point, they are often working with a smaller asset base. Buying protection or guarantees after a loss can feel like locking in the damage instead of planning ahead to avoid it. Agencies can help clients understand that the most effective timing is typically before a major market event, not after it.
Mistake 3: Overestimating How Long Health and Insurability Will Last
While many annuities do not require medical underwriting, a client’s age and health can still influence product availability, payout rates, and overall suitability. Waiting until health has noticeably declined can limit options or shift the conversation away from long-term planning and toward crisis management. Encouraging clients to plan while they are still healthy can preserve flexibility and choice.
Mistake 4: Ignoring Tax Planning Windows
There can be valuable tax planning windows between retirement and the start of required minimum distributions or Social Security. During those years, clients may be in a lower tax bracket, which can make it an ideal time to reposition assets into annuities as part of a broader, tax-aware strategy. Waiting too long can close that window and reduce the ability to manage distributions efficiently.
Schedule a Tax-Aware Retirement Strategy Call: 👉 https://cindybirkland.com/contact/
5. How Age Affects Annuity Options
Age is a crucial variable in annuity planning, not only because it affects life expectancy, but also because it influences which products are available and how they are structured. Agencies that understand these age-related dynamics can guide clients more confidently through the timing decision.
Clients in Their 50s: Laying the Foundation
In their 50s, many clients are still in peak earning years. They may not be emotionally ready to think about retirement income, but this is often an excellent time to lay the foundation with deferred annuities. Longer deferral periods can potentially translate into stronger future income guarantees, subject to the contract terms. For agencies, positioning annuities as one component of a long-term strategy rather than a last-minute fix can resonate well with this age group.
Clients in Their 60s: Transition and Income Planning
For clients in their 60s, the conversation often shifts from “someday” to “soon.” This is typically when they decide on retirement dates, Social Security claiming strategies, and how to turn savings into monthly income. At this stage, a mix of deferred and immediate income options may be appropriate. The key question becomes: how much income do they need guaranteed versus how much can remain in more flexible, market-based investments?
Clients in Their 70s and Beyond: Simplification and Longevity Risk
In their 70s and beyond, many clients are less focused on growth and more focused on simplicity and security. They may already be taking required minimum distributions and want to reduce the complexity of managing multiple accounts. Certain annuity options that provide lifetime income or help structure distributions can be valuable here, but product availability can narrow with age. This makes earlier planning beneficial, even if income is not needed right away.
6. Building a Timing Framework for Your Clients
To move from theory to practice, businesses and agencies can adopt a simple timing framework when discussing annuities with clients. Instead of asking, “Do you want an annuity?” consider walking through questions such as:
- When do you want to stop working, and when will you start drawing from your savings?
- How much of your monthly expenses do you want covered by guaranteed income sources?
- How would a major market downturn in the next five years affect your plans?
- Are there specific tax windows we can use to reposition assets more efficiently?
The answers can help you determine whether now is the right time to introduce annuities or whether it makes sense to plan for a future purchase date. In many cases, a phased approach works best: allocating a portion of assets to annuities at different stages rather than making a single all-or-nothing decision.
7. Bringing It All Together for Your Business or Agency
For organizations that support clients through retirement planning, the conversation about annuity timing is an opportunity to demonstrate leadership and clarity. Instead of focusing solely on product features, you can focus on sequence: when to introduce guarantees, how to coordinate them with Social Security and other assets, and how to adapt as clients age and markets change.
The right time to buy an annuity will look different for each client. Some will benefit from early positioning in their 50s, others from a targeted purchase at retirement, and still others from a later-life solution that simplifies income and addresses longevity risk. Your value lies in helping them see the trade-offs clearly and aligning decisions with their broader retirement vision, tax situation, and risk tolerance.
Schedule a Tax-Aware Retirement Strategy Call: 👉 https://cindybirkland.com/contact/
Mortgage services provided through North American Financial (NMLS #180736).375 N. Stephanie Street, Building 20 Henderson, NV 89014Insurance License #3103174 | NMLS #2106177
About Cindy Birkland
Cindy Birkland is a licensed insurance agent and retirement income specialist who focuses on helping individuals and families understand how income, taxes, and risk intersect in retirement. Her approach is educational, straightforward, and centered on clarity, so clients can make informed decisions with confidence.


